From questions to claims, a dedicated C&S account manager is ready to handle all of your car, truck, and motorcycle insurance needs. Let’s get started today.
From questions to claims, a dedicated C&S account manager is ready to handle all of your car, truck, and motorcycle insurance needs. Let’s get started today.
Tricks, Treats & Liability: What Homeowners Should Know This Halloween
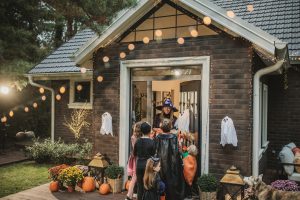
Halloween can be a fun time for families, friends, and neighbors to get together and celebrate the fall season. But did you know that Halloween, and trick-or-treating in particular, can be a tricky time for homeowners navigating liability claims?
It’s not uncommon for homeowner’s insurance claims to spike up to 14% on Halloween due to accidents. Typically, these involve trips and falls caused by lawn decor, cords, lack of lighting, ice, or other hazards.
Read on for our tips for preventing liability claims and what to do if someone gets injured on your property while trick-or-treating this spooky season.
How to Prevent Liability Claims on Halloween
Every state has its own rules on premises liability (the technical term for a property owner’s responsibility for visitor injuries), but a general rule of thumb is that homeowners owe their “highest duty of care” to people who have been invited onto their property.
This rule applies to explicit invites, such as the ones you extend for a party, or implicit invites, like turning on your porch lights or setting out a bowl of candy on your front steps on Halloween night. By taking these actions, you’re implicitly inviting trick-or-treaters onto your property, so you have a responsibility to ensure your property is safe.
As a property owner expecting visitors, you’re expected to take the following safety measures:
- Eliminating or minimizing dangers on your property, such as properly storing hoses, cords, toys, and lawn decor to avoid trips and falls
- Making sure stairs, walkways, porches, benches, chairs, and other features are safe for foot traffic or use
- Ensuring your property is sufficiently lit, especially at the top and bottom of stairs and along walkways
- Avoiding open flames (opt for battery-operated lights to set the scene instead)
- Posting signs or roping off unsafe areas to warn visitors about any dangers that can’t be fixed
- Keeping dogs and other animals away from visitors, especially if they have a history of overexcitement or aggression around strangers
By taking these steps, you can help keep visitors safe and avoid costly liability claims.
Common Halloween Hazards
To keep your home safe for Halloween guests, avoid these common safety concerns:
- Fire hazards, including candles (use battery-powered candles for your decorations and jack-o-lanterns instead)
- Unsecured figures, statues, and inflatables
- Cords and wires that run across high-traffic areas
- Uneven walkways, loose bricks, or broken handrails
- Slippery driveways, walkways, or stairs (whether from ice, rain, or rotting pumpkins)
- Inadequate lighting
- Treats that trigger food allergies (though you likely won’t be held liable for an allergic reaction to Halloween candy, unless you knew about a specific child’s allergy ahead of time)
- Dog bites (keep all pets inside the house and away from the door)
What If You Don’t Participate in Trick-or-Treating, But Trick-or-Treaters Come Anyway?
If you turn off your porch lights, leave your home undecorated, and don’t answer your door, it’s a clear signal you’ve opted out of trick-or-treating. Most insurers (and the law) wouldn’t consider this an implicit invitation.
If you’ve indicated that your home isn’t open for trick-or-treating, and trick-or-treaters show up anyway and get injured on your property, you won’t be held to the same standard as those who invite guests.
To avoid enticing trick-or-treaters to come to your home, close and latch all gates, turn off outdoor lights, keep doors closed, and avoid putting out welcoming decorations.
Does Homeowner’s Insurance Cover a Trick-or-Treater Getting Hurt on Your Property?
Yes, homeowner’s insurance will most likely cover someone getting injured on your property if you’re held liable.
Your policy doesn’t just cover their medical bills; it can also cover legal fees and provide an attorney to defend you if the injured party files a personal injury lawsuit. Liability coverage usually starts at $100,000, but standard homeowner’s policies can also have limits of $250,000 to $300,000.
In addition to liability coverage, many homeowner’s policies have a medical payments provision, sometimes listed as “Coverage F.” This is separate, distinct coverage intended to protect against minor incidents, and typically maxes out at $2,000 to $5,000. It covers the medical bills of someone who gets injured on your property, regardless of what caused the accident or who was at fault.
If you need broader protection than your homeowner’s insurance provides, you can purchase an umbrella liability policy, which adds additional liability protection onto your existing coverage.
What to Do If Someone Gets Injured on Your Property
If a trick-or-treater gets hurt on your property, here’s how the claims process works:
- Notify your insurance company or agent. Even if the injured party agrees to accept cash to cover their medical bills, they could still change their mind and file a lawsuit later. If you don’t notify your insurer right away, they could deny you coverage.
- The injured party files a claim. This will be a third-party claim under your liability coverage.
- The insurance company investigates the incident. They will determine whether or not you were at fault for the injury and if your negligence was the cause.
- If you weren’t at fault, the insurer denies the third-party claim, but the injured party may still file a lawsuit in court.
- Your insurer protects you in court. They have a duty to defend you, which means they will hire a lawyer to handle the case.
- The case likely results in an out-of-court injury settlement. It is rare for these cases to go to trial. But if it does, the insurer must still fight on your behalf and pay court awards up to your coverage limits.
Liability Coverage in New England
At C&S Insurance, we’re here for you this fall and during every season get a quote for a homeowner’s policy today. Or if you’re looking for broader liability coverage, explore our options for umbrella insurance.