You deserve more than a quick quote from a call center. That’s why at C&S Insurance, we offer personalized service and expert advice while shopping competitive rates from top carriers.
You deserve more than a quick quote from a call center. That’s why at C&S Insurance, we offer personalized service and expert advice while shopping competitive rates from top carriers.
What Happens if Your Landscaping Crew Damages a Customer’s Property?
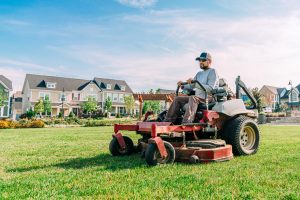
As a landscaper, you know the risks: Your mower tears up a sprinkler system or launches a rock through a window. Your skid steer hits a fence or knocks over a mailbox. Your equipment leaves ruts behind in someone’s lawn.
Not only do you face lost time and expensive liability claims when accidents like these happen, but you could also deal with bad reviews and a potential loss of trust in your business. Fortunately, with property damage insurance, a portion of your general liability policy, you can protect your business from unexpected costs.
Read on to learn more about property damage insurance, what it covers, what’s excluded, and tips for avoiding costly claims and keeping your clients happy.
Types of Property Damage Caused By Landscapers
Here are some of the most common ways landscapers cause damage on their clients’ property:
- A lawn mower throwing a rock into a window or glass door
- Backing a trailer into a garage door
- Damaging a sprinkler head
- Hitting a fence with a hedge trimmer or skid steer
- Cracking a driveway with a skid steer
- Chipping paint with a trimmer
- Damaging a stone or brick pathway
- Knocking over a mailbox
- Leaving ruts in a wet yard with heavy equipment
That said, many of these situations may be covered by a landscaping company’s property damage insurance policy, but exact coverages depend on its terms and limits.
What Is Property Damage Insurance?
It’s important for landscapers to carry property damage insurance. Generally, this is included as a part of your business’ general liability policy.
Property damage insurance shields your business from unexpected costs when your crew or equipment accidentally causes damage to someone else’s property, including yards, homes, and other structures. It covers the cost to repair or replace damaged fences, walkways, and other property, up to your policy’s coverage limits.
When a client files a property damage claim, your business will first have to pay the deductible (the amount you must pay out of pocket before your insurance kicks in). Generally, having a lower deductible means you’ll pay a higher monthly or yearly premium for your policy, but you’ll owe less in the event of a claim.
After you pay your deductible, your policy will then begin to cover the remaining costs and pay out the claim, up to the coverage limit. If the cost of damage exceeds the limit (e.g., your coverage limit is $100,000 and the damage costs $150,000), your business is responsible for paying the difference (in this case, $50,000).
What It Covers
For landscapers, property damage insurance usually applies to:
- Accidental damage to a home, yard, or structure
- Damage that occurs during landscaping work
- Damage caused by tools, machinery, or vehicles operating on-site
- Legal fees or settlements resulting from property damage claims
What’s Not Covered
It’s also important to understand what property damage insurance doesn’t cover for landscapers. Typically, the following situations are not covered:
- Damage to your own equipment or tools
- Intentional (not accidental) damage
- Employee injuries (these are typically covered by workers’ compensation)
- Damage caused by company vehicles while driving (accidents are usually covered by commercial auto insurance)
- Damage caused by subcontractors (unless they’re named on your policy or if the subcontractor carries their own property damage insurance)
- Damage occurring off-site (on properties that aren’t listed or jobs performed outside your typical work areas)
If you’re unsure of what coverage excludes, you can always double check your policy directly or with the help of an agent. The following situations may be covered by some policies, but not by others:
- Temporary employees or day labor
- Damage linked to a job error (faulty workmanship exclusions)
- Tree removal, grading, or hardscaping
Always be sure that your policy matches the way your business operates.
Who’s Liable?
When a landscaping crew damages a customer’s property, generally the landscaping company is held liable. But if something that hasn’t been disclosed to the crew is damaged, such as an unmarked utility line, the homeowner may be responsible for repairs. In some cases, the liability could be shared.
Avoid Property Damage Claims: Tips for Landscapers
Even when equipped with property damage insurance, the best policy is prevention. Here are four tips every landscaper should keep in mind to help avoid damage to client property.
1. Perform a jobsite walkthrough: Start each job by inspecting the property and identifying fragile, high-value, and/or items that can easily be damaged. These might include:
-
- Irrigation heads
- Retaining walls
- Outdoor lighting
- Freshly poured concrete
2. Provide proper training: Be sure your crew knows how to avoid damaging the items identified in your walkthrough. Regularly review how to properly handle equipment, loading and unloading protocols, and communication standards.
3. Document everything: If something looks damaged when your crew arrives on a jobsite, take a photo and talk to your client. If a client makes a last-minute request that could cause additional risks, let them know and get the request in writing.
4. Perform an equipment check: Before work begins, inspect your crew’s equipment for misaligned blades, unstable loaders, and other issues. Malfunctioning gear tends to cause damage more often than crew error.
Insurance for Landscapers in Massachusetts
At C&S Insurance, we know landscapers. We’ve been in the business of commercial insurance for more than 60 years, and we understand your landscaping company has specific coverage needs. We’re here to help you get a quote on general liability insurance and find the best policies for the best prices.