Got questions about your current insurance policy, or type of insurance coverage you think you may need? Find answers here, in our growing list of FAQs.
If you don’t see the information you’re looking for, please send your question to info@candsins.com. We’ll contact you with an answer – and turn your insurance FAQ into a quick infographic or video. Thanks for your help in highlighting today’s top-of-mind concerns!
To provide fast, reliable emergency clean-up and restoration assistance, we’ve teamed up with SERVPRO, one of the nation’s leading disaster recovery teams. If you need assistance after a disaster, please contact your dedicated SERVPRO contact directly. Your direct SERVPRO contact is: Tim Forbes, WRT, AMRT (508) 243-4228 Tim@TeamTMC.com Tim is a dedicated local SERVPRO representative […]
Read MoreYour C&S Insurance account manager is more than happy to help you process a personal or business claim. However, if you need claim support when our office is closed, please contact your carrier directly.
Read MoreYou can request a specialty insurance quote from us by getting in touch online, giving our team a call at 508-618-5975, or dropping by our Attleboro, Bridgewater, Dedham, or Mansfield offices.
Read MoreWhile home insurance rates in Massachusetts are influenced by factors like weather risks, rebuilding costs, and local claims trends, there are several steps you can take to help lower your premium. Consider bundling policies, increasing your deductible, improving home safety and security, avoiding small claims, asking about available discounts, and regularly reviewing your policy.
Read MoreWhat you’ll pay for home insurance in Massachusetts depends on a variety of factors and can differ widely from policy to policy. For an accurate estimate of what you’ll pay, getting a quote is a good first step.
Read MoreIf you own a swimming pool, your home insurance policy will likely include some coverage for damage to the pool itself. However, the much bigger risk is your personal liability if a guest were ever injured while swimming, diving, or playing in your yard. While you do get some level of personality liability coverage built […]
Read MoreCyber insurance, also known as cyber liability insurance, helps protect businesses from the financial fallout of data breaches, ransomware attacks, phishing scams, and other cyber incidents. These policies are designed to cover both the direct costs of an attack and the liability that can follow. If your business uses computers, stores customer or employee data, […]
Read MoreCoastal business property insurance is a stand-alone policy that covers risks associated with coastal properties, such as hurricanes, windstorms, flooding, and erosion. Generally, these are either excluded or undercovered in nearly all commercial property insurance policies due to the higher risks associated with insuring coastal properties.
Read MoreAt C&S Insurance, we offer specialized insurance coverage for a wide variety of industries, including: Arborist insurance Brewery insurance Cannabis insurance Construction insurance Electrician insurance Landscaper insurance Manufacturing insurance Waste Hauling insurance Pool Contractor insurance Landlord insurance Post-Acute Care Facility insurance And many more
Read MoreYou can request a business insurance quote from us by getting in touch online, giving the team a call at 508-618-5975, or dropping by our Attleboro, Bridgewater, Dedham, or Mansfield offices.
Read MoreContractor bonds, also called surety bonds, are financial guarantees that protect customers and the state if a contractor fails to follow laws, regulations, or the terms of a contract. Unlike other insurance coverages, which protect the contractor, bonds are designed to protect the public. In Massachusetts, certain contractor bonds are required, depending on the type […]
Read MoreCommercial business income insurance is a type of coverage that protects against loss of income due to damage to physical property. In addition to payroll, commercial business income insurance may also cover rent, the cost of moving (if needed), and more.
Read MoreCommercial auto insurance is a type of coverage intended to pay for losses involving cars, trucks, vans, and other vehicles that your business owns and uses for its purposes. In Massachusetts, this coverage is required if your business owns or uses vehicles for operations.
Read MoreProfessional liability insurance, also known as errors and omissions (E&O) insurance, is a type of coverage designed for businesses that provide services or advice to clients. If you or your employees make a mistake, give faulty advice, neglect something crucial, professional liability can provide the funds needed to correct the mistake. If necessary, professional liability […]
Read MoreYes. All Massachusetts employers are required to maintain this coverage for their employees and even for themselves, with a few exceptions to the rule: Owners of LLCs and sole proprietors may not be obligated to purchase coverage for themselves but would still need coverage for employees.
Read MoreA BOP is a simplified bundle of at least two essential business coverages, designed for small businesses in certain low-risk industries. Typically, a BOP includes key coverages such as general liability, business income, and commercial property. Notably, it doesn’t include workers’ compensation insurance or commercial auto coverage — these policies must be purchased separately.
Read MoreWhile general liability insurance isn’t mandated by the state, prospective clients or landlords may require businesses to carry a policy before agreeing to a contract or lease. Because of this, it’s in your best interest to purchase general liability coverage for your business.
Read MoreC&S Insurance offers business insurance coverages that include workers’ compensation, commercial auto, surety bonds, business owner’s policy, general liability, commercial property, professional liability, business income, and others. Our team of insurance professionals can help you find the policies that meet your needs.
Read MoreCondo insurance is a key type of coverage for condo owners, offering protection for the interior of your unit and your personal belongings. This variation of home insurance typically includes liability coverage, and it often helps with additional living expenses if your unit becomes uninhabitable due to a covered event. This type of coverage is […]
Read MoreEven though renter’s insurance isn’t legally required in Massachusetts, it’s a good idea to carry a policy if you rent your home as your landlord’s insurance doesn’t extend to you and your property.
Read MoreHigh net worth insurance is designed for houses, condos, and apartments that stand apart from other properties for their historical architecture, interior design, eco-friendly features, and/or overall value. If your home has a value of $2M or more, you need high net worth insurance.
Read MoreUmbrella insurance is a backup coverage that can help you pay for your legal defense or court-ordered settlements if the limits on your home insurance or car insurance aren’t enough. For anyone who owns a home, the answer is often yes. If you or a family member is ever named in a serious lawsuit (such […]
Read MoreNo, flood insurance is not included. Homeowners in flood-prone areas should consider purchasing separate flood insurance.
Read MorePolicies can vary quite a bit depending on your circumstances, but most at minimum include: Dwelling Coverage: Coverage for the physical structure(s) on your property (e.g., the house or building and anything attached to it) Liability Coverage: Coverage for any injuries or damages that occur on your property (or possibly even elsewhere) Property Coverage: Coverage […]
Read MoreWhen it comes to lowering your monthly car insurance bill, there are several options you can pursue. Shopping around for a new insurer, asking your current carrier about discounts (e.g., safe driver, low mileage, good student, or bundling), increasing your deductible, improving your credit score, and practicing safe driving habits can go a long way […]
Read MoreThe latest state mandates (as of July 2025) require the following minimum coverages: Bodily Injury to Others: $25,000 per person / $50,000 per accident Personal Injury Protection (PIP): $8,000 per person, per accident Bodily Injury Caused by Uninsured Auto: $25,000 per person / $50,000 per accident Damage to Someone Else’s Property: $30,000 per accident
Read MoreYes. Massachusetts law requires all drivers to carry auto insurance with specific minimum coverage limits.
Read MoreAt C&S Insurance, we offer a variety of different personal coverages including auto, renter’s, home, condo, high net worth, coastal property, and umbrella insurance. Our team is here to help you find the coverages you need.
Read MoreYacht coverage is typically broader since these larger vessels often travel on longer journeys, which increases the risks for perils and exposures. Boats and other watercraft tend to stay closer to shore.
Read MoreThe majority of watercraft policies allow anyone to operate your boat, as long as you give permission for them to do so.
Read MoreThese boats are examples of watercraft that may be covered as part of your homeowners insurance. Many homeowners’ policies include a $1,500 limit for small watercraft kept on premise. If your canoe or kayak has a value that’s higher than this limit, it may make sense to explore a separate policy.
Read MoreIt’s possible for your home insurance policy to extend to your boat or other watercraft. Typically, if the vessel is under a certain size and value, it will be covered either in part or in full. To be safe, it’s always best to verify with your home insurance provider.
Read MoreYou should insure your boat or other watercraft for its “agreed value,” or the amount it would take to replace it.
Read MoreStandard watercraft policies typically include coverage for accidents, lost or damaged items, physical damage to the vessel, towing and wreckage removal, fuel spills, and legal costs. We recommend choosing an “all risk” policy. With this type of watercraft insurance plan, all losses that aren’t specifically omitted are covered.
Read MoreYes. Without food truck insurance, you will be responsible for covering costs associated with any lawsuits, interruptions to business, and/or property damage that may arise — potentially leading to the closure or loss of your business.
Read MoreWhen it comes to determining policy premiums, there’s no one-size-fits-all approach, and what you pay will depend on several factors that are unique to your food truck business.
Read MoreAt minimum, your food truck business must carry commercial auto and workers’ compensation insurance, as these are requirements in Massachusetts. However, we highly recommend opting for a more comprehensive policy to mitigate the other risks associated with food truck ownership.
Read MoreWhat your policy covers will depend on the types of coverages you select. With a comprehensive policy in place, you can expect coverage for auto accidents, business interruptions, legal liability, property damage, workers’ compensation, and more.
Read MoreBefore you shop for business insurance, you’ll want to shop for a reputable business insurance agency. This is because many commercial insurance companies don’t sell directly to customers. They rely on agents, who understand the underwriting process, to gather required information and present it in a standardized way. Even in cases where carriers are willing […]
Read MoreJust like price, recommended coverage limits are dependent on a variety of factors unique to your company. In some cases, third parties (like your landlord or your clients) may require you to carry certain levels of coverage. As your business grows and evolves, it often makes sense to revisit your various policy limits.
Read MoreBusiness insurance agents act as advocates for company owners and leaders, by securing all the necessary types of protection, with optimal coverage limits. The best business agents have access to many different commercial insurance carriers (we work with three dozen!), which translates into more options and more competitive rates. Thanks to longstanding relationships with top-tier […]
Read MoreBusiness insurance costs, per year, run an enormously wide range, from a few hundred dollars at the least, up to millions of dollars for the largest corporations. Broadly speaking, the cost of your business insurance will depend on your industry, the size of your company (in terms of gross sales and payroll), and your insurance […]
Read MoreThe Bay State sets minimum required limits as follows: Bodily injury liability: $25,000 per person / $50,000 per accident Uninsured motorist bodily injury (UMBI): $25,000 per person / $50,000 per accident Property damage liability: $30,000 per accident Personal injury protection (PIP): $8,000 per person, per accident
Read MoreIn the state of Massachusetts, there are only two required types of business insurance: Workers’ compensation insurance Commercial auto insurance (unless your business never owns or hires any vehicles)
Read MoreBusiness insurance is essentially a protection plan, designed to ensure that a company doesn’t suffer serious financial losses in the aftermath of events including (but not limited to) natural disasters, employee injuries, or customer lawsuits. Most often, having “business insurance” means having a collection of different policies. These individual policies address different types of business […]
Read MoreIf your business is on or near the coast, then insuring it for the types of severe weather and natural disasters associated with coastal proximity is of paramount importance. If a weather event were to take place, you could find yourself paying hundreds of thousands of dollars out of pocket to repair the damage.
Read MoreClaims related to fire, lightning strikes, tornado damage, water damage, and severe weather are almost always excluded from coverage. Coastal insurance, by contrast, offers much more comprehensive coverage that includes provisions for events that typical property insurance excludes.
Read MoreYes. It’s in your best interest to have a homeowners insurance policy at the very least, but more comprehensive coverage is recommended to offset the unique risks associated with owning property close to the shore.
Read MoreEvery home and property is unique, which means that there’s no “best” option — only what’s best for you. Some common coverages include high-value home insurance, flood insurance, vacation home insurance, and umbrella insurance.
Read MoreWhen it comes to determining policy premiums, there’s no one-size-fits-all approach, and what you pay will depend on several factors that are unique to your situation.
Read MoreHomeowners insurance of any kind is not required in Massachusetts. However, it is strongly recommended that you carry a policy.
Read MoreSpecific event coverages will depend on the types of supplemental insurance you add to your policy. However, when you submit a claim, you can expect dwelling, liability, property, and additional living expenses coverages.
Read MoreCertain types of construction company insurance, such as workers’ compensation, are typically required by law in most states. The requirements vary by state and the number of employees employed. Additionally, many construction contracts require contractors and builders to have specific insurance coverages, such as general liability, commercial auto, and builders’ risk. Even if construction insurance […]
Read MoreConstruction business insurance is essential to protect your construction company against unforeseen risks and liabilities that may arise during your operations. This includes damage to property, injuries to employees or third parties, and accidents or mishaps that may occur during the construction process. Furthermore, many construction contracts require contractors and builders to have certain types […]
Read MoreConstruction and contracting professionals should consider: The type of coverage and limits required to adequately protect their business The financial stability and reputation of the insurance company The cost of the policy Coverage that mitigates the potential risks associated with their operations and projects The claims history of the insurance company Customer service reviews
Read MoreWhen comparing construction insurance brokers, developers, builders, and contractors should consider several factors, including: The broker’s level of expertise in the construction industry The range of insurance products and services offered The quality of customer service provided The broker’s reputation and history of successful placements Whether the broker can provide customized solutions to meet their […]
Read MoreDevelopers, builders, and contractors should consider several factors when comparing construction insurance programs, including: The type and scope of projects they undertake The size and nature of their business operations Coverage and limits provided Customer service reviews
Read MoreYes. Most clients won’t risk working with uninsured plumbers. Additionally, being underinsured can leave you vulnerable to liabilities, lawsuits, and financial loss, so it’s always best to carry a comprehensive policy.
Read MoreEvery plumbing business is different, which means that there’s no “best” option — only what’s best for you. Some common coverages include general liability, commercial auto, professional liability, and commercial property.
Read MoreWhen it comes to determining policy premiums, there’s no one-size-fits-all approach, and what you pay will depend on several factors that are unique to your plumbing business.
Read MoreAt minimum, licensed plumbers in Massachusetts must carry liability insurance.
Read MoreWhen you submit a claim, you can expect coverage for auto accidents, bodily injury, business interruptions, legal liability, loss or theft of tools and equipment, property damage, and workers’ compensation.
Read MoreSome types of coverage that self-employed electricians should consider are: general liability, commercial property insurance, professional liability, commercial auto, and umbrella. Each business is unique, so it’s always best to speak with an agent about your needs.
Read MoreSince policies are made to fit individual needs, there’s no one-size-fits-all approach to determining premiums. Some of the considerations that impact the cost of electrician insurance are: number of employees, cost of assets, industry, etc.
Read MoreElectrician insurance is made from a bundle of specific types of business coverages. It’s designed to protect all businesses that provide electrical services from property- and liability-centered risks.
Read MoreNo, landlord insurance does not kick in if your tenants do not pay rent. However, typical landlord insurance policies do cover instances where the rental property becomes uninhabitable due to a covered loss.
Read MoreWhen shopping for a landlord insurance policy, you should ensure that property damage, personal liability, and loss in income coverages are included. Beyond those basic coverages, you may want to consider adding supplemental coverage for vandalism, burglary, flood, and earthquake damage if the area where the property is located is considered high risk.
Read MoreNo, landlord insurance is not applicable for shared properties. In this case, since you live in the dwelling where you rent out space, landlord insurance would not apply.
Read MoreThis refers to a statement or summary of your coverage, which verifies that your business is insured.
Read MoreAccording to the IRS, in most cases you can deduct the cost of insurance as a business expense if it’s for your business or profession.
Read MoreGeneral liability insurance products a business against third-party claims involving accidents, bodily injury, or property damage. It’s also known as small business liability insurance or commercial liability insurance. Professional liability insurance protects your company from lawsuits claiming negligence, misrepresentation, violation of good faith and fair dealing, or inaccurate advice.
Read MoreYes, expenses related to company-owned vehicle accidents and employee injuries are covered by your landscapers liability insurance policy.
Read MoreThe cost of your landscapers insurance policy can vary depending on a number of considerations. Key factors that can influence the price of coverage include the size of your business and number of employees, whether you offer certain higher-risk services such as tree removal, the number and types of company vehicles you operate, the location […]
Read MoreIf you work in or adjacent to the landscaping industry, your business faces unique risks. A landscapers liability insurance policy helps keep your business protected from financial loss resulting from employee or client injuries, property damage, equipment theft, and more. Furthermore, you may be required to carry landscapers insurance in order to obtain state licensure, […]
Read MoreThe cost of commercial business insurance depends on your company’s insurance needs. The main variable is gross sales over the past 12 months.
Read MoreBusiness income insurance is attached to your property policy.
Read MoreAny business can apply for commercial business income insurance.
Read MoreCommercial business income insurance is a type of coverage that protects against loss of income due to damage to physical property.
Read MoreYou can get a flat deductible which is a simple number of $1,000 or $2,500. Many carriers may offer policies based on the percentage of the hull. For example you could have a $100,000 boat with a 2% deductible. Therefore you would have a $2,000 deductible.
Read MoreThere are two main parts to a yacht insurance policy: hull insurance and protection and indemnity insurance, according to Investopedia. If your yacht is an antique or classic vessel, you may also look for specialized coverage.
Read MoreYacht coverage is typically broader since these larger vessels often travel on longer journeys, which increases the risks for perils and exposures. Boats tend to stay closer to shore. Yacht insurance will also typically include natural disaster coverage since there’s a greater chance they could encounter inclement weather.
Read MoreYou may be able to receive what is called a “lay up” discount. It’s best to give us a call to discuss your year-round coverage possibilities.
Read MoreThe majority of boat insurance policies allow anyone to operate your boat, as long as you’ve provided permission. There may be some exceptions, though, so it’s best to carefully read through your policy and confirm with your C&S insurance agent before you agree to let someone else behind the wheel.
Read MoreA typical boat insurance policy will cover property damage and help replace or repair any personal items that may have been lost or damaged. A policy will also cover a large portion of any medical expenses if there is an accident, regardless of whether you or someone else driving your boat is at fault (or […]
Read MoreYou should insure your boat for the amount it would take to replace it — otherwise known as “agreed value” coverage.
Read MoreWe recommend an “all risk” policy.
Read MoreWhile your business insurance policy may cover any of your equipment that might be damaged, any employees working from their own home will be responsible for damage to their own property. They should consult their own homeowners’ policy to see how they’re covered.
Read MoreYou’re still responsible! That’s why it’s vital to have home workers’ insurance, especially if they’re considered full-time at more than 16 hours a week.
Read MoreIf you have a home worker who works remotely, you still bear the same responsibilities as their employer and so still need to invest in home worker insurance or another form of business liability insurance. Policies do differ so it is best to check with your carrier to make sure that liability extends to the […]
Read MoreYou can, but only if you are a home-based business. If you just have a nanny, workers’ comp insurance is an entirely separate policy. If you have a home-based business and a nanny, they are separate and cannot be bundled. Always consult with a local agent (we’re just a call away) to get the best […]
Read MoreIt depends. A home-based business is like any other business and will require different insurance policies depending on the specific set of risks. Homeowners insurance will not cover everything, so you may need to consider: Liability insurance to protects against accident and injury, especially if you have clients on site Property insurance to cover specialize […]
Read MoreThe cost will depend on a number of factors, including the type and breed of your pet, the pet’s age, where you live, and whether your pet has any pre-existing conditions.
Read MorePre-existing conditions, annual exams, vaccinations, and spaying and neutering are usually not covered.
Read MorePet insurance typically covers accidents and illnesses, hospitalization, surgeries, prescriptions, cancer treatments, and vet specialists.
Read MorePet insurance is not required, but it provides the financial security and peace of mind you need to keep your pets as safe and healthy as possible. You probably have a good idea of what routine visits and vaccinations cost, but an unexpected trip to the vet could set you back thousands of dollars.
Read MoreAny licensed vet in the U.S., Canada or Puerto Rico accepts vet insurance.
Read MorePet insurance is the equivalent of health insurance for humans. You pay an annual premium for certain types of coverage that will help reduce your overall pet expenses. In some cases, you will pay the healthcare provider directly, such as when you visit a hospital, you pay your deductible and the insurance providers works out […]
Read MoreIf you live in campus housing, you are most likely covered by your parent’s insurance. It’s a good idea to confirm the details since some policies only cover student property up to a certain percentage of your household’s total coverage. If you live off-campus, you will need your own insurance coverage.
Read MoreIf your luggage gets stolen during a vacation or work trip, your Massachusetts renter’s insurance will probably cover the loss, but it’s not always a guarantee so make sure to review your policy.
Read MoreThe average renter’s insurance cost in Massachusetts is between $15 and $30 a month.
Read MoreNo, but it’s recommended. Some landlords may require their tenants to hold renter’s insurance.
Read MoreNo two breweries operate the exact same way. That’s why our agents like to understand each breweries’ unique operations and risks. We typically ask for a 30-minute call or meeting to discuss the operations and get to know what’s important to you. It’s a very simple process, and we’re happy to walk anyone through it. […]
Read MoreThere are a handful of companies that can provide coverage for breweries and microbreweries in Massachusetts and throughout New England. While many carriers can provide insurance for one specific line of coverage, it is in the business owner’s best interest to bundle everything into one program. We have access to insurance companies that are capable […]
Read MoreThe exact cost will depend on a number of locations, the company’s gross sales (alcohol sales), food sales, property insured, and many other factors.
Read MoreThere are many types of bundled coverages, but some of the most important types of insurance include general liability, commercial auto, workers’ compensation, and professional liability.
Read MoreWorkers in the tree care industry face a number of hazards, such as overhead power lines, falling branches or trees, and defective equipment. It’s important to work with an insurance agent who understands your company’s unique coverage needs.
Read MoreMost companies in the tree care industry need some type of arborist insurance, including tree removal/land cleaning specialists, tree trimmers and pruners, landscapers, tree pest management professionals, and hardscaping professionals.
Read MoreGeneral liability protects against third-party claims involving bodily injury and/or property damage that may occur on a job or business site. At minimum, BOPs include general liability coverage and property coverage.
Read MoreThis refers to any property your company owns within your business, which can include stock, materials, ingredients, betterments and improvements, and property located outside and within a specified distance to the building, etc.
Read MoreIt depends on the type of risk and the type of company. Other factors that will affect the price include a company’s loss history, the size of the business, and how many buildings the company owns. There are a lot of factors, and every business is different, so give us a call, and we’d be […]
Read MoreGreat question. The best way to find out is to contact a licensed, local agent — like the ones who make up our commercial lines team. Here at C&S, we’ve been advising Massachusetts business owners for 60+ years. Connect with us at 508-594-3424.
Read MoreTypically, a BOP bundles together key coverages like general liability and commercial property. Companies can also purchase add-on coverages to supplement a basic BOP.
Read MoreA BOP is a simplified bundle of at least two essential business coverages designed for small businesses in certain low-risk industries, with specialized pricing over other liability and property policies
Read MoreOur agents can generate quotes based on a completed application and a 30-minute call to discuss the operations/timeline/deliverables. It’s a very simple process, and we’re happy to walk anyone through it. Just call our team at 508-594-3936.
Read MoreThere are a handful of companies who can provide coverage for the entire spectrum of cannabis-based businesses (in Massachusetts and throughout New England). While many carriers can provide coverage for one specific line of coverage, it is in the businessowner’s best interest to bundle everything into one program, to achieve economies of scale. We have […]
Read MoreIf a business elects to purchase professional liability, then yes, training and education can certainly help impact rates in a positive way. Knowing the products and how they might affect an individual is a significant exposure. The more knowledgeable the employee is, the better.
Read MoreNo two businesses will have the same rates. But there are ways to estimate what your premiums might cost, even as a cannabis startup. Annual revenue and crop valuation are the key drivers of premium. The cost of your general liability policy, for example, is based on expected revenue during the policy year, using a […]
Read MoreAs the state of Massachusetts inches toward approving wholesale marijuana delivery (currently only available for medicinal buyers), this is an important question. The answer is still evolving. For now, depending on the carrier, it does seem that commercial auto coverage will offer some amount of “goods in transit” coverage, which would address instances of theft […]
Read MoreThese coverages would be most applicable to cannabis cultivators in Massachusetts and New England. Product recall deals with tainted product that needs to be pulled from circulation due to mold, yeast, or bacteria that prevents the plant from yielding a quality product. Affected products would not pass the required testing process in Massachusetts. If the […]
Read MoreProfessional liability coverage deals with what the company or employee recommends/suggests to a customer (e.g., a specific product that will work well or solve a problem) either in person or as advertised on a website. In the event that a customer experiences a negative result based on said recommendation, a professional liability claim could arise. […]
Read MoreProduct liability is a common one. (See more on product liability below.) Unless specifically requested, it is not included in a general liability policy. Also, Tenants Improvements & Betterments (TIB) are often overlooked. This coverage is for the money invested to build out the physical location; it is NOT building coverage. Building coverage protects the […]
Read MoreThe bundle approach is preferable to start. Depending on the business’ insurable values, there may eventually be a “layering” of carriers, in order to achieve certain coverage limits. However, for a less-established cannabis business (i.e., in their first 5 years of operation) a bundled program will work for 9 out of 10 companies.
Read MoreNo. Since condo insurance is a type of homeowners insurance, one or the other is sufficient.
Read MoreLoss assessment is an optional coverage that you can add on to a home or condo insurance policy.
Read MoreCondo insurance is not required by Massachusetts law, but we recommend that everyone has it. Most condo associations will require you to have a condo insurance policy.
Read MoreCondo insurance is a type of insurance specifically for condominium homeowners.
Read MoreCommercial auto insurance can cover damages due to collisions, accidents, property damage involving a covered vehicle.
Read MoreThat depends on what state your business is based. In Massachusetts, commercial liability vehicle insurance is required.
Read MoreCommercial auto insurance is a type of coverage intended to pay for losses involving cars, trucks, vans, and other vehicles that operate while doing business.
Read MoreThe deductible amount depends on the policy. It also depends how property is insured. The insurance company may pay upfront and then send you the deductible, or they will pay for your claim up to your coverage limit, minus the deductible amount. For example, if your $30,000 Bobcat loader is stolen and you have a […]
Read MoreIt’s important to insure your property to its full value. Depending on the insurance policy, partially insured property may not be covered in a loss.
Read MoreThe cost of commercial property insurance will vary due to factors like property value, location, number of properties, industry, and risks.
Read MoreCommercial property insurance helps cover physical damages or loss of physical property, including includes building structures, furniture, signage, inventory, equipment, and other property.
Read More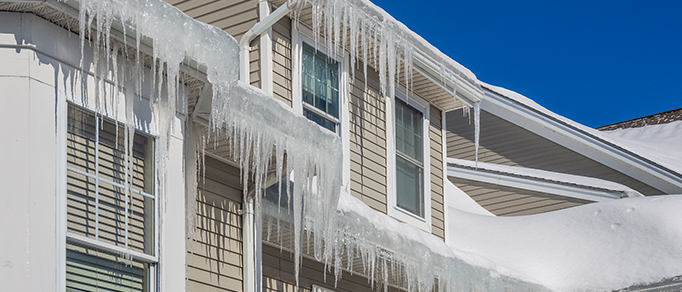
After hurricanes and tornados, severe winter weather is the third biggest cause of catastrophic homeowner losses. Read these simple steps to learn how to prevent ice dams.
Read More
Employment practices liability suits can arise from a variety of situations: sexual harassment, wrongful termination, discrimination, retaliation, and more… This infographic attaches hard numbers to EPL risks, so you can see where your business stands.
Read More
Too many companies—especially small and mid-sized businesses—are still vulnerable to cyber attacks. Get the facts you need to protect your reputation and your bottom line.
Read More